Jump to a section
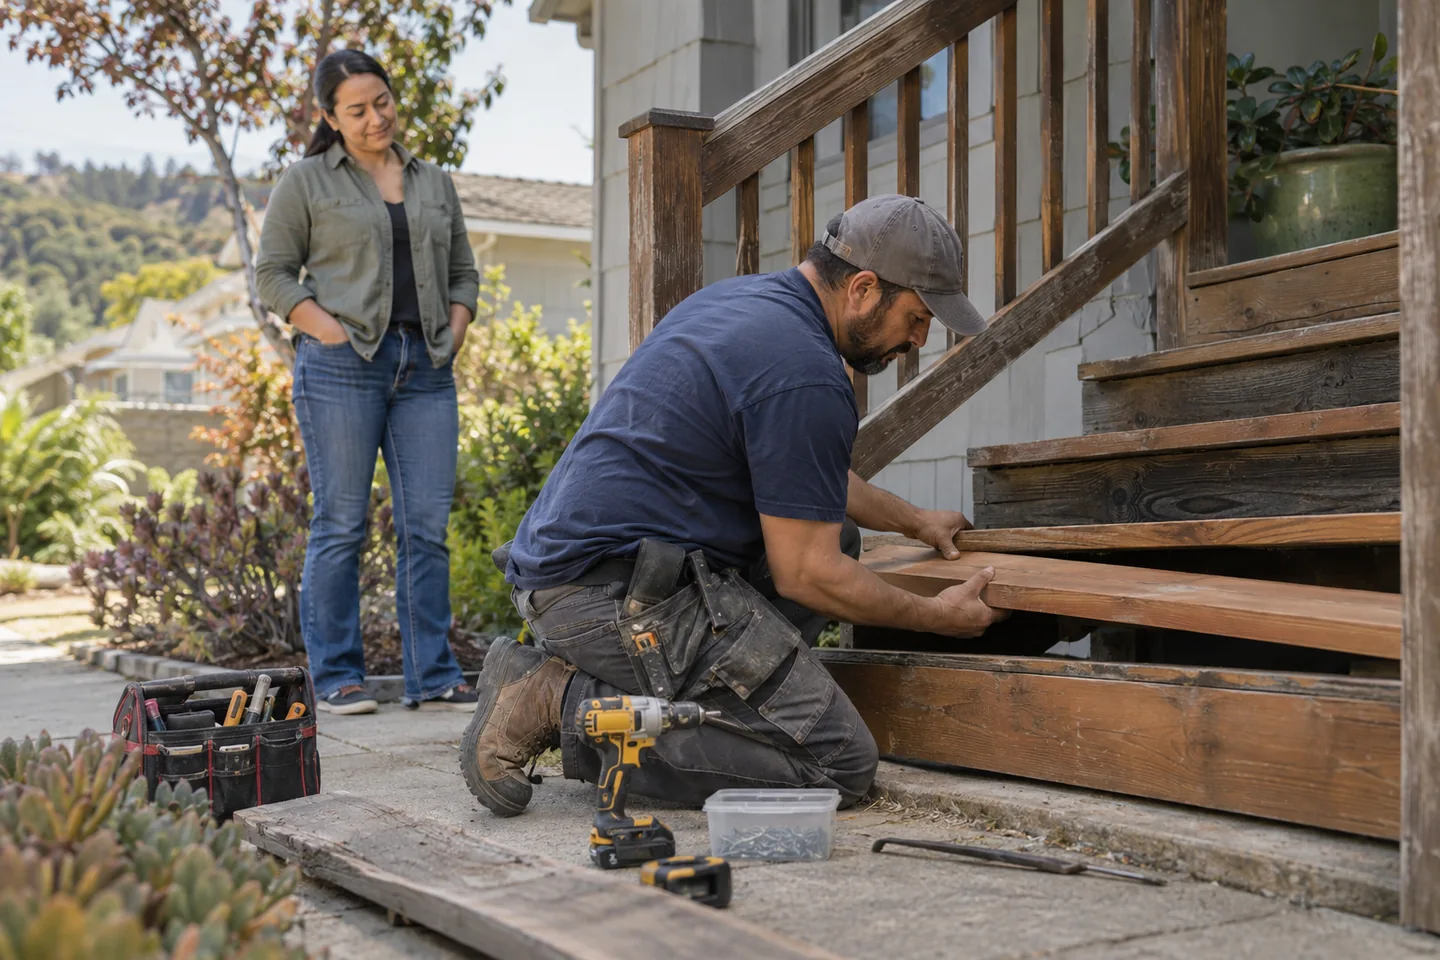
In an FHA/HECM discussion, possible repair requirements raised a timing concern. Chipped paint was one of the issues being considered, and we explored whether another financing path might help.
The first question was not whether the repair sounded small.
What is actually required, how long will it take, and what does each option cost?
Get the written requirement first
A possible issue and a formal lender condition are different things.
Ask for the appraiser's finding and the lender's explanation. What work is needed? Who can do it? Does it need another inspection? What must happen before closing?
A photo or the word “chipped” is not enough to decide the loan requirements. The property and applicable rules provide the context.
Compare three paths
- Complete the work: Get a scope, price and realistic schedule that the lender accepts.
- Allow more time: If the loan otherwise fits, compare the consequences of waiting.
- Review another loan: Tell that lender about the actual condition before assuming the product change solves it.
Changing financing is not a promise that another lender will ignore the issue.
Count the cost of changing direction
Look at new fees, appraisal work, any lock extension and the payment under the alternative loan.
Separate money already spent from what would be spent next. Then ask what happens if the repair takes longer or uncovers more work.
A faster closing is not automatically the better answer if it creates an uncomfortable payment for years afterward.
The deadline matters. So does the homeowner's longer-term goal. I would put the time, cost and remaining uncertainty beside each option before choosing a path.
This example is based on a real mortgage discussion with identifying information removed. Any numbers are illustrative and are not current loan terms or a commitment to lend. Loan programs, rates, property values and borrower qualification vary.
Sources and further reading
Keep exploring
Related questions
Stay ahead of the next move
Choose the updates worth opening.
Get the Morning Market note on rates and markets, the housing update, or both. You choose what lands in your inbox.
Know What We Know