Taxes & mortgage payments
Your mortgage servicer changed. What should you do first?
A new mortgage servicer means new payment instructions, not a new loan. Use this checklist to protect your payment, escrow and records during the handoff.
FOR PLACER COUNTY HOMEOWNERS
A new mortgage servicer means new payment instructions, not a new loan. Use this checklist to protect your payment, escrow and records during the handoff.
Understand the 2% rule, temporary value reductions, tax-bill charges and the steps to take when your county assessment looks too high.
Received a California supplemental property tax refund after buying a home? Learn why it may happen, what to verify and why the money may still be needed.
Homeowners insurance helps protect your home and belongings against covered losses. In California, start checking insurance availability and cost early in a home purchase, and review coverage before renewal. A mortgage preapproval is not confirmation that a particular property can be insured. Compare coverage, exclusions, deductibles and the total cost, then have your lender review the proposed policy.
The California FAIR Plan is limited property coverage and is not equivalent to a traditional homeowners policy. A separate Difference in Conditions policy, often called DIC, may address gaps such as liability, theft and certain water damage. Actual coverage depends on both policies. Have a licensed insurance professional explain the gaps and have your lender review the complete proposed coverage.
Read the notice and identify the policy expiration date, the stated reason and the insurer's contact details. Contact your insurance professional promptly and start shopping for replacement coverage. Keep your mortgage servicer informed. Ask the California Department of Insurance about notice requirements or protections that may apply to your address; do not assume a nonrenewal notice ends coverage immediately or that an exception automatically applies.
Your new payment may include both a higher amount for future insurance bills and repayment of an existing escrow shortage. Those are separate items. A fixed mortgage interest rate does not freeze taxes or insurance costs. Review the servicer's escrow analysis, compare its insurance figure with the actual renewal premium and ask it to explain the shortage calculation and repayment schedule.
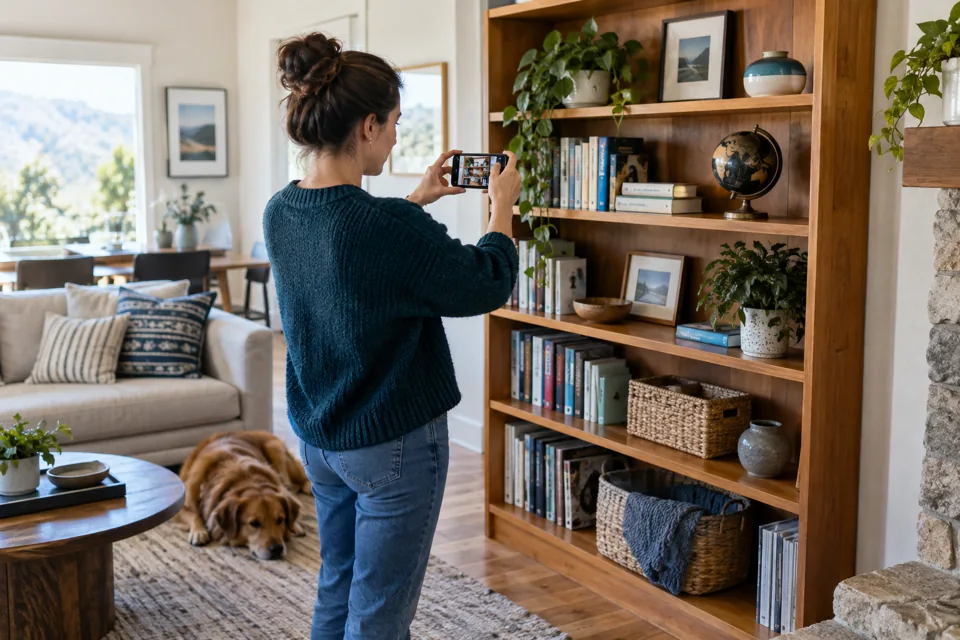
Start room by room and create a usable record of belongings before a loss.
Use the renewal to review the home, limits, exclusions and changes in your household.