Quick answers
Open a question. Read the answer right here.
What should I prepare before seeking renovation financing?
Define the scope, contractor path, permits, timeline, contingency and property value questions before deciding which loan structure fits.
Jump to a section
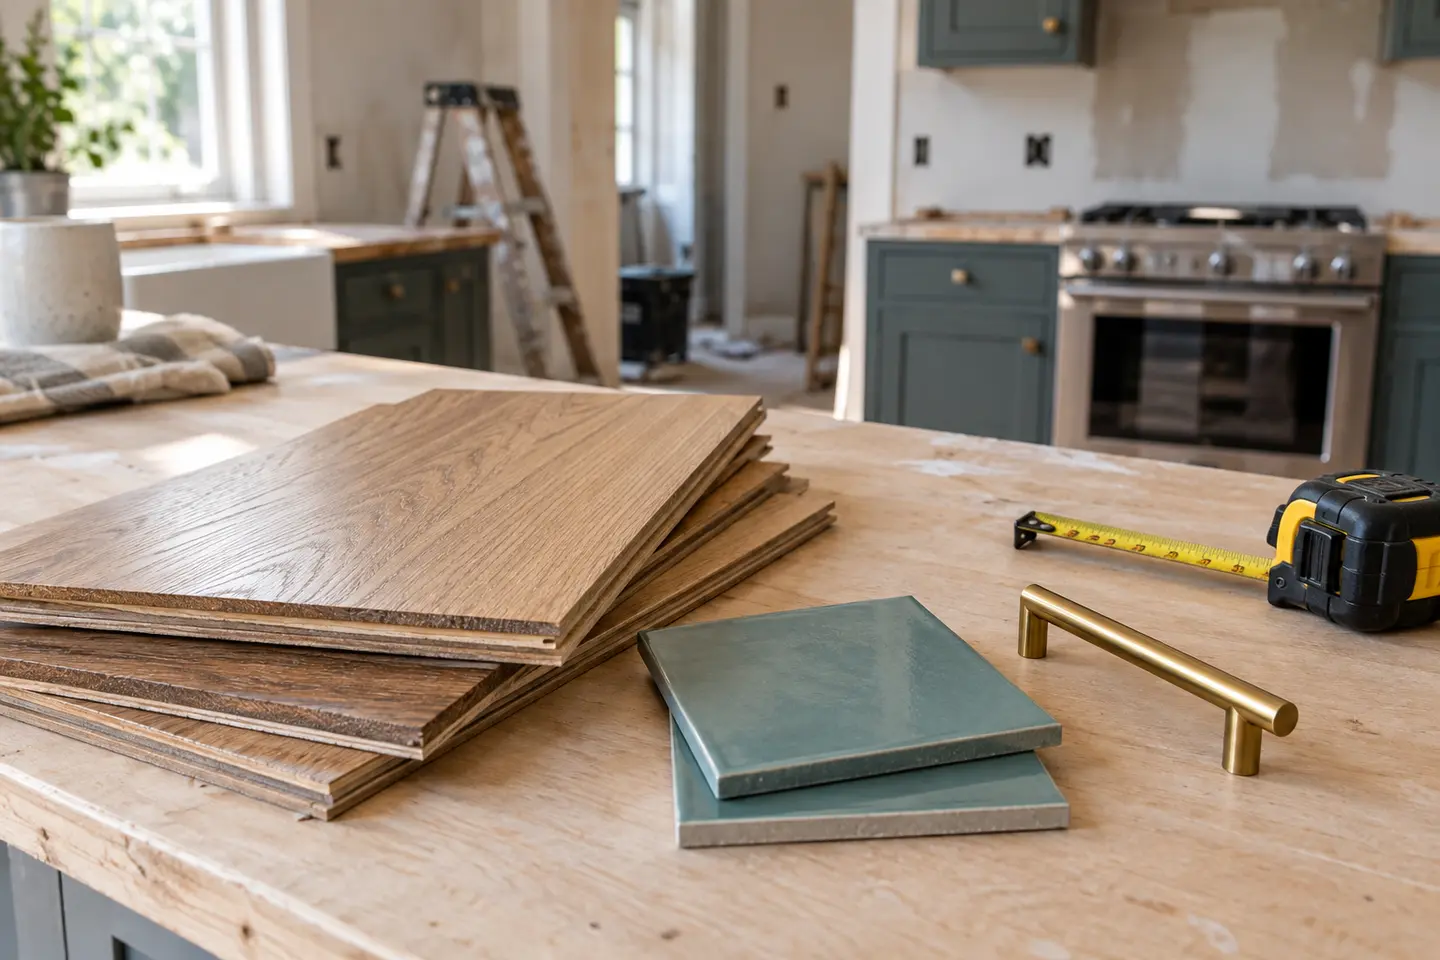
The project must become legible before the financing can
Renovation financing depends on a credible description of the work. Separate required repairs from desired improvements, identify permits and design needs, and develop a realistic contractor scope. A rough wish list is not enough to evaluate cost, timing, value, or loan structure.
The early plan should also identify whether the property can be occupied during construction, whether health or safety issues exist, and which work may affect eligibility. These questions shape the financing path before an appraisal or draw schedule is discussed.
Contingency is part of the budget
Existing homes reveal surprises. Demolition can expose water damage, electrical issues, structural conditions, or outdated systems. A budget without contingency assumes the most optimistic version of the project.
Financing rules may define which costs can be included and how funds are controlled. The homeowner still needs a plan for items outside the approved scope and for delays that affect temporary housing or carrying costs.
Draws and inspections change the contractor relationship
Renovation funds are often released as work is completed and verified rather than handed over at closing. Contractors need to understand documentation, licensing, draw timing, change orders, and inspection requirements before committing to the project.
A contractor who is excellent at construction but unprepared for controlled draws can create stress for everyone. Process compatibility belongs in contractor selection.
Value is an analysis, not a renovation fantasy
Some financing relies on an after-improved value, but cost does not guarantee equal value. Design choices, neighborhood expectations, market conditions, and appraisal evidence all matter.
The responsible plan connects the desired home, credible construction budget, available financing, and realistic value support. If those pieces do not align, changing the project before closing is usually easier than changing it mid-build.
A practical sequence
- Separate required repairs from desired improvements
- Build a realistic scope and contingency
- Confirm contractor and permit expectations
- Compare after improvement and current value questions
- Choose financing after the project plan is credible
Questions worth bringing to the first conversation
Ask which repairs are required, what permits and contractor documents are needed, and how draws and inspections work. Identify a budget for overruns, delays, temporary housing, and work that financing may not cover.
Where professional judgment enters
The facts of the borrower, property, program and timing determine which questions become decisive. Use this guide to prepare, then verify the current rules and scenario with the appropriate licensed professionals.
Continue the question
- Using home equity for repairs and improvements
- FHA increased the maximum draw requests for Limited 203(k) loans
- Same equity. Different ways to borrow.
What should I prepare before seeking renovation financing?
Define the scope, contractor path, permits, timeline, contingency and property value questions before deciding which loan structure fits.
Sources and further reading
Use the source below to read the agency’s guidance and check for later changes.
203(k) Rehabilitation Mortgage Insurance Program Types (new tab)
Keep exploring
Stay ahead of the next move
Choose the updates worth opening.
Get the Morning Market note on rates and markets, the housing update, or both. You choose what lands in your inbox.
Know What We Know