Quick answers
Open a question. Read the answer right here.
Who is the counselor, and whose side are they on?
A HECM counselor works through a HUD-approved counseling agency and must be on HUD's HECM counselor roster. The counselor's role is to explain your options impartially, not recommend a particular lender or sell a loan. You choose the agency. Your lender cannot conduct the session for you.
Use HUD's reverse mortgage counseling directory (new tab) to find an agency. Ask about appointments, fees, language assistance and who needs to attend. Telephone, video or in-person availability also depends on applicable state requirements.
Will the counselor ask me questions?
Yes. This is more than listening to a presentation. HUD's protocol requires the counselor to check your understanding with questions throughout the discussion. For example, you might be asked to explain which home expenses remain your responsibility or what could make the loan due. These examples describe the topics, not an answer sheet.
If something is unclear, say so. The counselor can explain it another way and may need another session. A certificate may be withheld when understanding is inadequate or when coercion or fraud is suspected. The goal is an informed decision, not memorizing words to finish an appointment.
Who needs to attend?
For HECM counseling, the prospective borrower, a non-borrowing spouse and any non-borrowing owner must receive counseling. Trusts and legal representatives require closer attention, so describe those arrangements when booking rather than assuming one person can speak for everyone.
You can also ask to include an adult child or another trusted person. Optional family support does not replace the required participant's understanding or turn that person into a borrower. Tell the agency if you need an interpreter, hearing assistance or another accommodation.
What does counseling cost?
There is no single nationwide price. Ask for the agency's fee before booking and explain if paying it would be difficult. HUD-approved agencies must disclose charges in advance, and the CFPB explains that they cannot charge a fee you cannot afford. Ask how the agency evaluates fee relief. Counseling charges are separate from the loan's closing and ongoing costs. See the CFPB's counseling and loan cost explanation (new tab).
Jump to a section
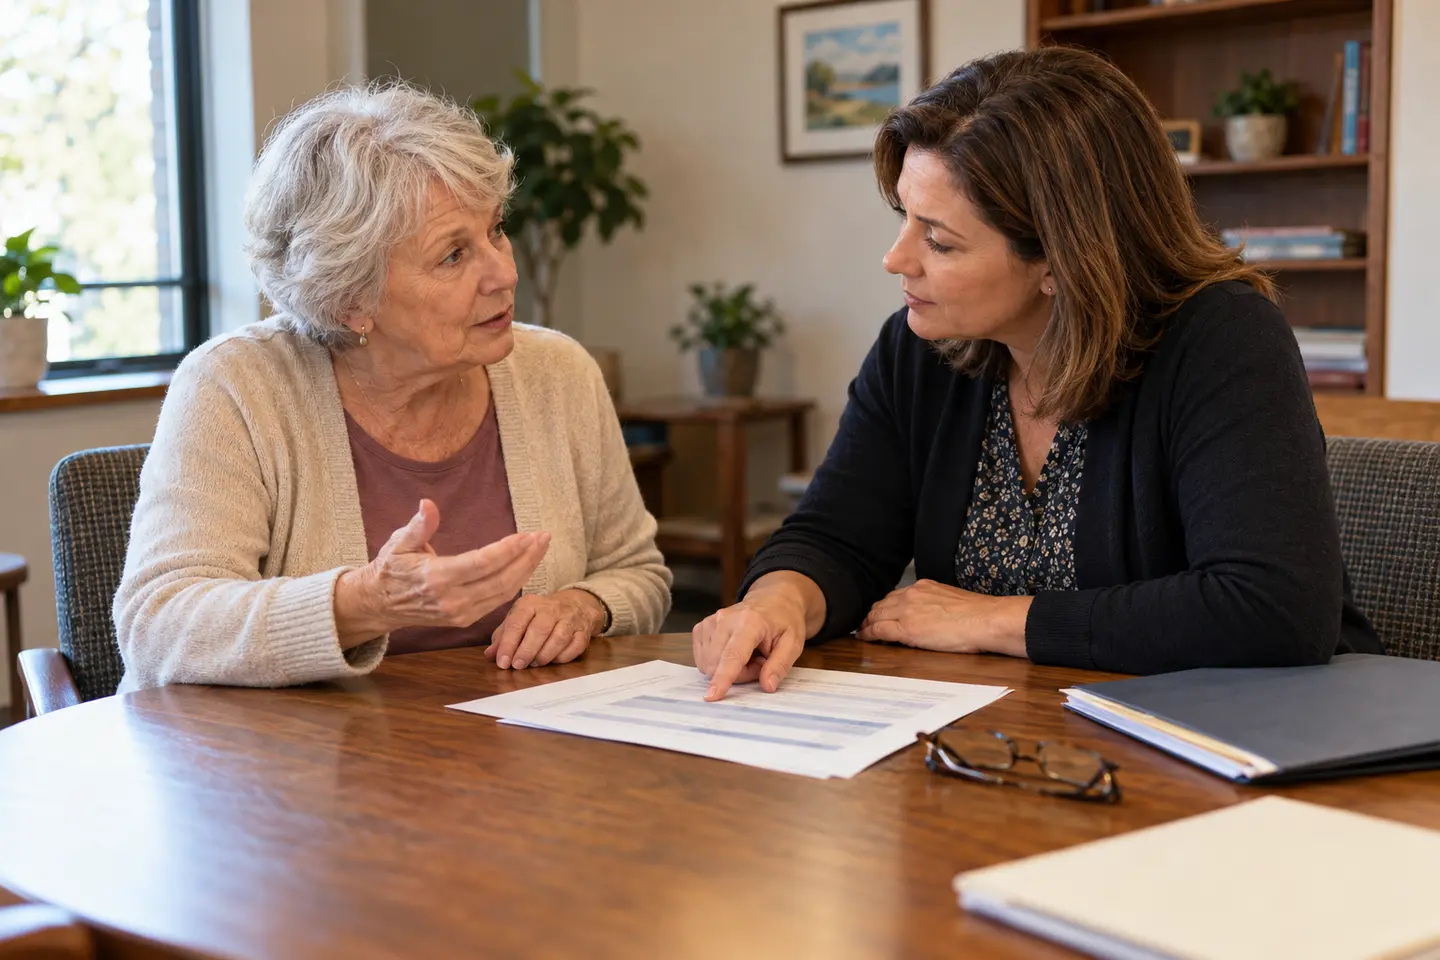
Reverse mortgage counseling is an independent educational conversation about how the loan works, what it costs, what you must keep paying, and the alternatives. For a Home Equity Conversion Mortgage (HECM), the federally insured reverse mortgage, counseling is required. Completing it does not obligate you to borrow, and a counseling certificate is not loan approval.
You may arrive with one practical question: could my home equity make retirement more manageable? Counseling makes room for the questions that follow. What happens to the balance? Could my spouse stay in the home? What if our plans change?
You do not need to arrive convinced that a reverse mortgage is right for you. You need room to understand it.
Who is the counselor, and whose side are they on?
A HECM counselor works through a HUD-approved counseling agency and must be on HUD's HECM counselor roster. The counselor's role is to explain your options impartially, not recommend a particular lender or sell a loan. You choose the agency. Your lender cannot conduct the session for you.
Use HUD's reverse mortgage counseling directory (new tab) to find an agency. Ask about appointments, fees, language assistance and who needs to attend. Telephone, video or in-person availability also depends on applicable state requirements.
Before the appointment: gather your real-life questions
Ask the agency what it wants you to review or provide. For HECM counseling, the preparation packet includes loan comparisons, a total annual loan cost calculation and an amortization schedule showing how a balance could change. Read them, and circle anything you cannot explain in your own words.
- Your budget: income, regular expenses, property taxes, insurance, association dues and likely repairs.
- Your home: the current mortgage balance, other liens and any trust or ownership arrangements.
- Your household: who owns the home, who lives there, and what each person expects if you move or die.
- Your goal: what you hope the loan would solve, and how long you expect to stay.
Share sensitive records only through the agency's secure process. HUD’s sample appointment letter suggests about an hour or longer if needed. Confirm the time with your agency and leave room for questions.
During counseling: follow the money and the responsibilities
The discussion connects the loan to your household, rather than stopping at a list of features. Expect to discuss how proceeds can be received, the existing mortgage that would need to be paid off, upfront costs and the effect of interest and fees on the balance.
A HECM generally has no required monthly principal-and-interest payment. That does not remove the obligation to pay property taxes and insurance, maintain the home and meet occupancy requirements. Failing those obligations can put the home at risk. Ask how you would cover these expenses if insurance rises or a major repair arrives.
Then look ahead. Discuss selling, moving to a care facility, death and what a spouse or heirs would need to do. A spouse's protection depends on the circumstances and program requirements; do not assume everyone living in the home can remain indefinitely. The CFPB's questions for a reverse mortgage counselor (new tab) are a useful starting point.
Compare alternatives, too: staying without a new loan, downsizing, assistance programs, or other financing with its own payments and qualification requirements. Ask what each option would change in your budget.
Will the counselor ask me questions?
Yes. This is more than listening to a presentation. HUD's protocol requires the counselor to check your understanding with questions throughout the discussion. For example, you might be asked to explain which home expenses remain your responsibility or what could make the loan due. These examples describe the topics, not an answer sheet.
If something is unclear, say so. The counselor can explain it another way and may need another session. A certificate may be withheld when understanding is inadequate or when coercion or fraud is suspected. The goal is an informed decision, not memorizing words to finish an appointment.
Who needs to attend?
For HECM counseling, the prospective borrower, a non-borrowing spouse and any non-borrowing owner must receive counseling. Trusts and legal representatives require closer attention, so describe those arrangements when booking rather than assuming one person can speak for everyone.
You can also ask to include an adult child or another trusted person. Optional family support does not replace the required participant's understanding or turn that person into a borrower. Tell the agency if you need an interpreter, hearing assistance or another accommodation.
What does counseling cost?
There is no single nationwide price. Ask for the agency's fee before booking and explain if paying it would be difficult. HUD-approved agencies must disclose charges in advance, and the CFPB explains that they cannot charge a fee you cannot afford. Ask how the agency evaluates fee relief. Counseling charges are separate from the loan's closing and ongoing costs. See the CFPB's counseling and loan cost explanation (new tab).
After counseling: a certificate is a starting point
If counseling requirements are met, the agency issues the counseling certificate. A HECM certificate is valid for 180 calendar days from the date counseling is completed. It documents counseling; it does not approve the borrower, approve the property or recommend the loan.
You can continue, pause or decide against borrowing. If you continue, the lender still has to complete its application, property and financial reviews. State requirements can also affect timing. Ask about the timeline for your situation before making commitments.
This article focuses on HECMs. Proprietary reverse mortgages are different products and are not federally insured. Ask which counseling and certificate requirements apply to the specific product. HUD describes the HECM process in its March 2026 housing counseling handbook, Chapter 4 and Appendix 1 (PDF, new tab).
Leave with answers you can use
Before ending the session, write down three things: the obligations you would keep, what happens if your housing plans change, and the alternatives you still want to compare. Ask the counselor to revisit any answer that remains uncertain.
Counseling is useful even when the result is waiting or choosing a different path. Your home and your retirement deserve that space.
Keep exploring
Stay ahead of the next move
Choose the updates worth opening.
Get the Morning Market note on rates and markets, the housing update, or both. You choose what lands in your inbox.
Know What We Know