Jump to a section
Can the other unit’s rent help me qualify for a Roseville duplex?
Yes, eligible documented rent from the unit you will not occupy may help. In the FHA illustration here, $2,200 a month in supported rent produces $1,650 under a 75% calculation. The lender must still approve the property, documentation and full loan scenario.
Quick answers
Open a question. Read the answer right here.
How much of the rent can count?
Do not plan on using every dollar of rent to qualify. For an FHA purchase with no rental history on the property, the calculation generally uses 75% of the lower of the appraiser’s market rent or the lease rent. The rent must be supported by the required appraisal and rental documentation. HUD Handbook 4000.1, rental income
For illustration:
| Supported monthly rent from the tenant’s unit | 75% calculation |
|---|---|
| $2,200 | $1,650 |
| $2,300 | $1,725 |
That is a 25% reduction, rather than a 10% vacancy allowance. It is an underwriting calculation, not a promise that actual repairs, vacancies, and other expenses will stay within that amount.
Conventional financing also commonly uses a 75% calculation when qualifying with leases or appraiser-supported rents. Fannie Mae’s guidance includes restrictions tied to the buyer’s current housing payment and rental-management experience. We need to confirm those facts and the applicable lender rules before deciding how the income enters the qualification calculation. Fannie Mae rental-income guidance
The unit the buyer will occupy does not contribute hypothetical rent to this owner-occupied scenario. We are evaluating one rental unit, not two. Fannie Mae general rental-income rules
What rent should we use while shopping in Roseville?
The rental examples below are a research snapshot from September 21, 2026.
For an initial two-bedroom example, I would model $2,200 a month and also check the numbers at $2,300. These are working assumptions, not an appraisal of a home the buyer has not selected.
One Roseville duplex listing on Kent Street reports existing rents of $2,200 and $2,225 for its two-bedroom units. Its $775,000 asking price is above this buyer’s target, so it provides rent context rather than an example of a $600,000 purchase. Those rents are listing-reported, not independently verified leases. Local duplex listing
For contrast, Estia Roseville advertises two-bedroom duplex homes with different features and community amenities at higher rents, including a listed starting rent of $2,775. I would not transfer that figure to an older duplex simply because both are in Roseville. Estia floor plans and advertised rents
Once there is an address, we can compare similar units nearby and review the actual lease. Bedrooms, condition, parking, outdoor space, and who pays utilities all belong in that comparison.
FHA or conventional with a small down payment?
At a $600,000 purchase price, these are useful starting points:
| Financing option | Potential minimum down payment | Dollar amount |
|---|---|---|
| FHA, if eligible | 3.5% | $21,000 |
| Eligible conventional owner-occupied duplex through automated underwriting | 5% | $30,000 |
FHA’s minimum down payment can be 3.5%. Fannie Mae’s standard automated-underwriting matrix allows up to 95% financing on an eligible two-unit principal residence. The familiar 3%-down conventional option is for eligible one-unit homes; it is not the standard duplex option. HUD down-payment overview · Fannie Mae eligibility matrix
So, with only 3% to 4% set aside for the down payment, FHA deserves a close look. Conventional would mean finding another $9,000 for the down payment compared with FHA in this example.
Those figures are down payments, not total cash needed to close. Closing costs, prepaid expenses, and any required reserves need their own budget. The comparison also needs actual interest rates and mortgage-insurance costs. A 680 score alone does not tell us which option costs less or fits better.
I would compare both options on the same property and ask: What is the full monthly payment, how much cash remains after closing, and can the buyer handle a vacancy or a major repair?
How long would the buyer need to live there?
For FHA, at least one borrower generally must move in within 60 days of signing the security instrument and intend to live there for at least a year. This must be a genuine principal residence. HUD Handbook 4000.1, principal residences
Keeping the duplex as a rental later is a possibility to discuss, not a guaranteed move-out date. Before moving, review the signed loan’s occupancy obligations, insurance, and rental requirements. For a conventional loan, confirm the specific occupancy terms in that loan’s documents as well.
An occupied duplex also raises a practical question: will the buyer’s unit actually be available in time? Have the agent review existing tenancies before assuming either side can become the buyer’s home.
What happens next?
This buyer is still shopping. There is no selected duplex or completed purchase to report.
When a property looks promising, I would want to review its price, unit layout, lease, supported rent, taxes, insurance, condition, and available move-in date alongside the buyer’s approval. We would also confirm housing-payment history, any landlord experience, and the funds available after closing.
The rent can help, but I want the buyer to be comfortable owning the property when the other unit needs a repair or sits empty between tenants.
Thinking about buying a duplex? Send us the address you are considering. We can help you compare the financing and understand how the other unit’s rent may fit.
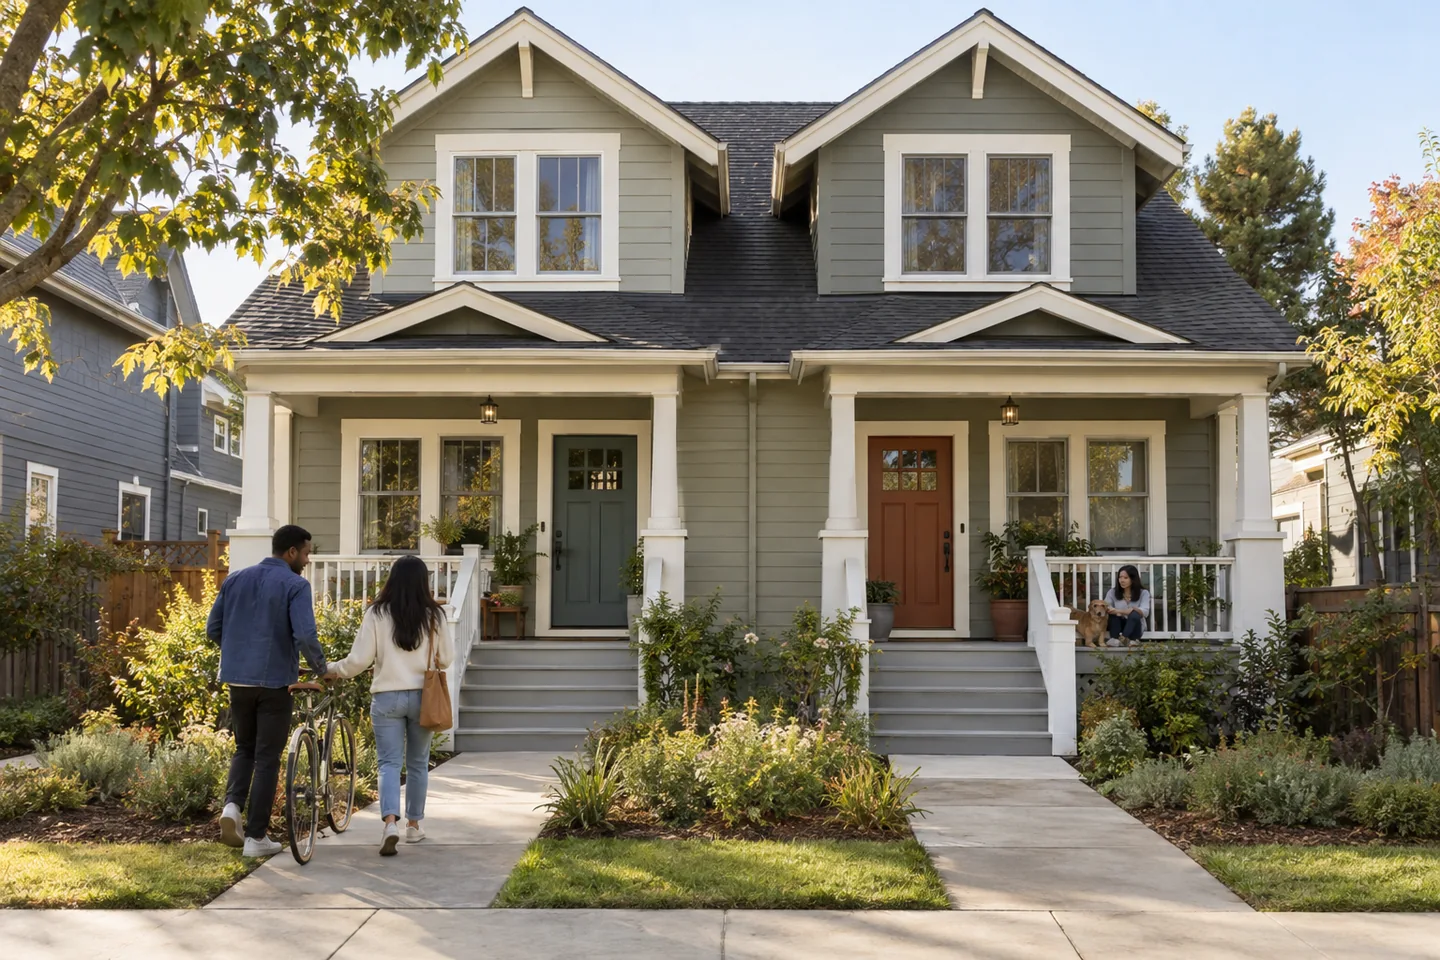
A first-time buyer is shopping for a duplex in Roseville with a straightforward plan: live in one side and rent out the other.
The buyer is approved, understands their financing options, and is still looking for the right property. The question now is how a particular duplex fits that approval, and what happens if they eventually move out and keep it as a rental.
Here is the scenario:
| Detail | Buyer’s starting point |
|---|---|
| Target purchase price | About $600,000 |
| Annual income | $120,000, or $10,000 gross monthly |
| Credit score | 680 |
| Student loan payment | $350 per month |
| Other debt | None reported; an extra $200 monthly cushion is being considered for credit cards |
| Available down payment | Exploring options around 3% to 4% |
| Property | Not selected yet; rent and unit sizes still need verification |
The $200 is a planning allowance, not a confirmed credit-report payment. We would use the documented obligations when reviewing the actual loan.
How much of the rent can count?
Do not plan on using every dollar of rent to qualify. For an FHA purchase with no rental history on the property, the calculation generally uses 75% of the lower of the appraiser’s market rent or the lease rent. The rent must be supported by the required appraisal and rental documentation. HUD Handbook 4000.1, rental income
For illustration:
| Supported monthly rent from the tenant’s unit | 75% calculation |
|---|---|
| $2,200 | $1,650 |
| $2,300 | $1,725 |
That is a 25% reduction, rather than a 10% vacancy allowance. It is an underwriting calculation, not a promise that actual repairs, vacancies, and other expenses will stay within that amount.
Conventional financing also commonly uses a 75% calculation when qualifying with leases or appraiser-supported rents. Fannie Mae’s guidance includes restrictions tied to the buyer’s current housing payment and rental-management experience. We need to confirm those facts and the applicable lender rules before deciding how the income enters the qualification calculation. Fannie Mae rental-income guidance
The unit the buyer will occupy does not contribute hypothetical rent to this owner-occupied scenario. We are evaluating one rental unit, not two. Fannie Mae general rental-income rules
What rent should we use while shopping in Roseville?
The rental examples below are a research snapshot from September 21, 2026.
For an initial two-bedroom example, I would model $2,200 a month and also check the numbers at $2,300. These are working assumptions, not an appraisal of a home the buyer has not selected.
One Roseville duplex listing on Kent Street reports existing rents of $2,200 and $2,225 for its two-bedroom units. Its $775,000 asking price is above this buyer’s target, so it provides rent context rather than an example of a $600,000 purchase. Those rents are listing-reported, not independently verified leases. Local duplex listing
For contrast, Estia Roseville advertises two-bedroom duplex homes with different features and community amenities at higher rents, including a listed starting rent of $2,775. I would not transfer that figure to an older duplex simply because both are in Roseville. Estia floor plans and advertised rents
Once there is an address, we can compare similar units nearby and review the actual lease. Bedrooms, condition, parking, outdoor space, and who pays utilities all belong in that comparison.
FHA or conventional with a small down payment?
At a $600,000 purchase price, these are useful starting points:
| Financing option | Potential minimum down payment | Dollar amount |
|---|---|---|
| FHA, if eligible | 3.5% | $21,000 |
| Eligible conventional owner-occupied duplex through automated underwriting | 5% | $30,000 |
FHA’s minimum down payment can be 3.5%. Fannie Mae’s standard automated-underwriting matrix allows up to 95% financing on an eligible two-unit principal residence. The familiar 3%-down conventional option is for eligible one-unit homes; it is not the standard duplex option. HUD down-payment overview · Fannie Mae eligibility matrix
So, with only 3% to 4% set aside for the down payment, FHA deserves a close look. Conventional would mean finding another $9,000 for the down payment compared with FHA in this example.
Those figures are down payments, not total cash needed to close. Closing costs, prepaid expenses, and any required reserves need their own budget. The comparison also needs actual interest rates and mortgage-insurance costs. A 680 score alone does not tell us which option costs less or fits better.
I would compare both options on the same property and ask: What is the full monthly payment, how much cash remains after closing, and can the buyer handle a vacancy or a major repair?
How long would the buyer need to live there?
For FHA, at least one borrower generally must move in within 60 days of signing the security instrument and intend to live there for at least a year. This must be a genuine principal residence. HUD Handbook 4000.1, principal residences
Keeping the duplex as a rental later is a possibility to discuss, not a guaranteed move-out date. Before moving, review the signed loan’s occupancy obligations, insurance, and rental requirements. For a conventional loan, confirm the specific occupancy terms in that loan’s documents as well.
An occupied duplex also raises a practical question: will the buyer’s unit actually be available in time? Have the agent review existing tenancies before assuming either side can become the buyer’s home.
What happens next?
This buyer is still shopping. There is no selected duplex or completed purchase to report.
When a property looks promising, I would want to review its price, unit layout, lease, supported rent, taxes, insurance, condition, and available move-in date alongside the buyer’s approval. We would also confirm housing-payment history, any landlord experience, and the funds available after closing.
The rent can help, but I want the buyer to be comfortable owning the property when the other unit needs a repair or sits empty between tenants.
Thinking about buying a duplex? Send us the address you are considering. We can help you compare the financing and understand how the other unit’s rent may fit.
This example is based on a real mortgage discussion with identifying information removed. Any numbers are illustrative and are not current loan terms or a commitment to lend. Loan programs, rates, property values and borrower qualification vary.
Sources and further reading
Keep exploring
Related questions
Mortgage glossary
Stay ahead of the next move
Choose the updates worth opening.
Get the Morning Market note on rates and markets, the housing update, or both. You choose what lands in your inbox.
Know What We Know