Jump to a section
In one file, the loan program changed after a conventional appraisal. The first conversation was about correcting the report.
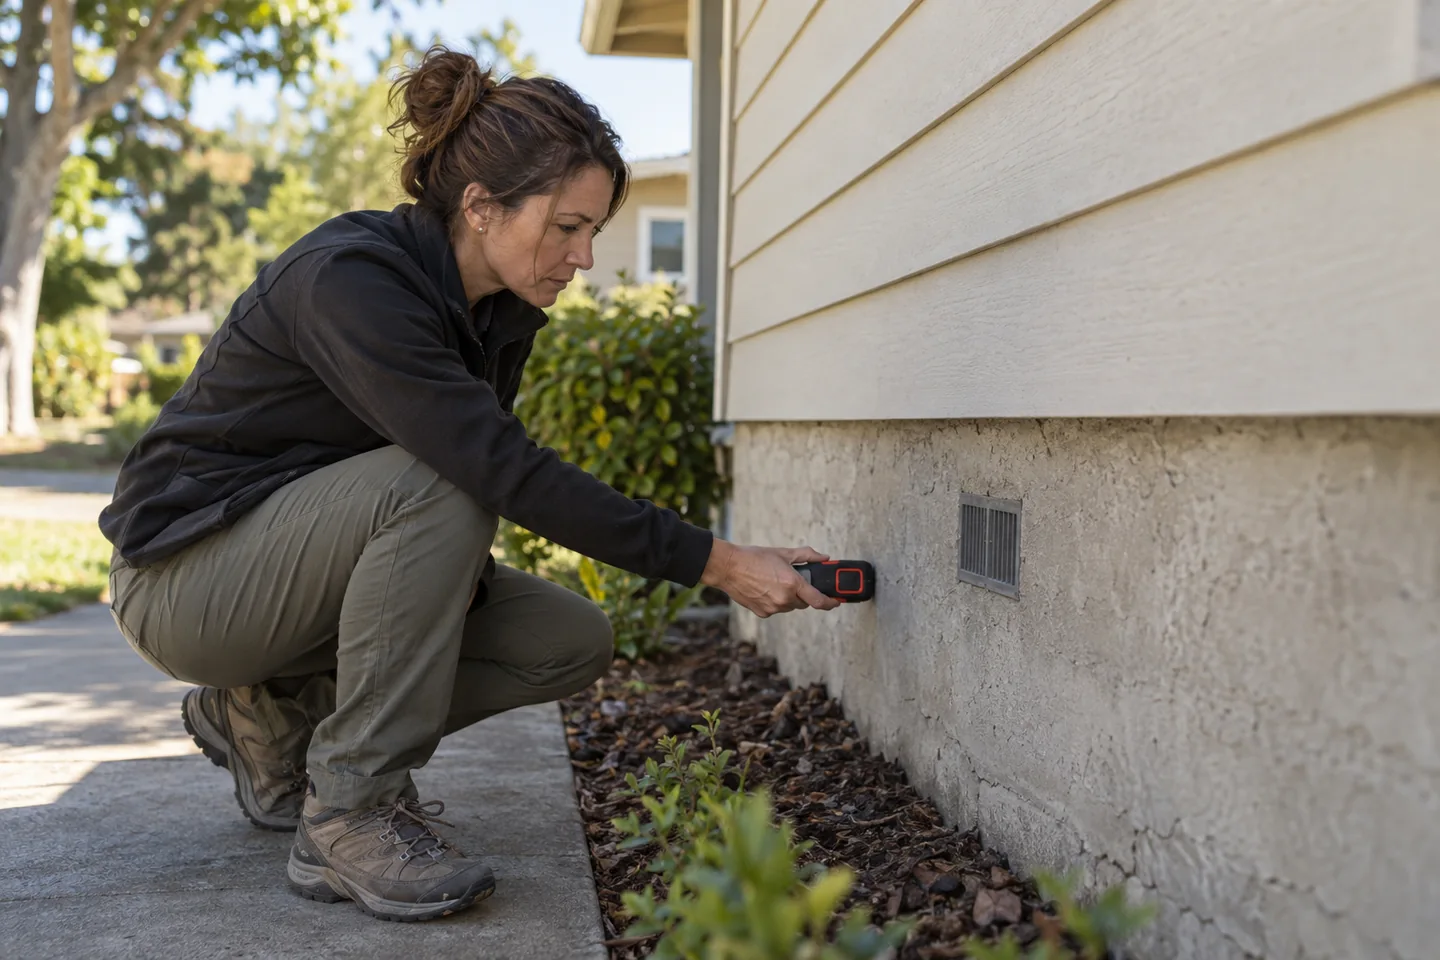
Then the appraisal team explained that more FHA-related inspection work was needed, including attention to the attic.
This was more than changing a label on a report.
Find out what the FHA review needs
Before assuming we can reuse an appraisal, I want the lender and appraisal team to review the original assignment and inspection.
Does the report meet the requirements for the new loan? Is additional work possible and acceptable? Is a new appraisal needed?
Adding an FHA case number alone does not answer those questions.
Turn the answer into a closing plan
If more work is required, ask:
- Who will order it?
- Does the appraiser need access to the home again?
- What will it cost?
- When can the work be completed?
- When can the lender review it?
A report correction, another inspection and a replacement appraisal are different tasks. We need to know which one is actually needed.
Recheck the rest of the loan too
If another issue caused the program change, we should revisit the remaining loan conditions at the same time.
Solving the appraisal question does not automatically finish the income or property review.
I would rather identify the extra work while we can still arrange it than have everyone discover it when they expect to sign.
The useful answer is what this specific appraisal can support and what still needs to happen, not a blanket yes or no about reusing appraisals.
This example is based on a real mortgage discussion with identifying information removed. Any numbers are illustrative and are not current loan terms or a commitment to lend. Loan programs, rates, property values and borrower qualification vary.
Sources and further reading
Keep exploring
Related questions
Stay ahead of the next move
Choose the updates worth opening.
Get the Morning Market note on rates and markets, the housing update, or both. You choose what lands in your inbox.
Know What We Know