First-Time Buyers
Buying a home? Know your options before asking for a price cut
Compare a lower price, closing-cost help, temporary payment relief and rate options around the cash you need and the payment you can sustain.
First-Time Buyers
Compare a lower price, closing-cost help, temporary payment relief and rate options around the cash you need and the payment you can sustain.
AI in Real Estate
Faster document processing is useful only if it improves the loan experience. Track repeat requests, waiting time and actual costs before judging an AI promise.
Mortgage Guides
A refinance title waiver may remove one lender requirement, not every title service or homeowner risk. Compare the itemized costs and protections.
Mortgage Guides
Strong savings may support a mortgage when commissions fall, but the lender still reviews your assets, obligations, loan terms and sustainable payment.
Reverse Mortgages
HomeSafe Second preserves your first mortgage, but adds a second balance that can grow. Compare payments, costs, equity and repayment before choosing it.
Mortgage Guides
A backyard unit’s advertised rent does not count dollar for dollar. Learn what the lender must verify before using ADU income for your mortgage.
First-Time Buyers
Manual review and down payment assistance are separate approvals. Compare repayment, forgiveness, monthly cost and future refinance consequences.
Housing & Communities
A sharp rally in builder shares can arrive before stronger home sales. Here is how to separate market expectations from evidence at the sales office.
Housing & Communities
Rising sale prices do not erase buyer leverage. Learn how comparable sales, competing listings, market time and condition can support your offer.
Rates & Economy
A hot inflation report can push mortgage rates higher, but competing bond-market forces can reverse the move. Here is what a better quote means.
Homeownership
A new mortgage servicer means new payment instructions, not a new loan. Use this checklist to protect your payment, escrow and records during the handoff.
AI in Real Estate
When an AI tool reads a mortgage document, who can explain the result? Two conversations with Brian Vieaux show why the answer matters for lenders and borrowers.
Appraisal review
Understand a high CU score, secondary valuations, CDA reviews and broker price opinions, plus what a lower value could mean for your home equity loan.
Mortgage rates
See a 2-1 buydown payment example, Fannie Mae seller-contribution limits, and how to divide a seller credit between payment relief and closing costs.
Mortgage rates
See a worked mortgage-payment and refinance break-even example, and build a homebuying budget that works without a future rate drop.
Retirement
See how eligible retirement assets can become mortgage qualifying income, with a worked asset-depletion example and a practical retirement budget checklist.
Home value
Compare a $15,000 price cut with a seller credit, check Roseville-area listing history and sales, and budget for repairs before making an offer.
Buying a home
A Refer result is a request for closer review. Learn a California FHA manual-underwriting path, see a debt-to-income example, and understand assistance repayment.
Buying a home
Understand pocket listings, off-market homes and MetroList’s On Market Date, with a buyer script and a practical repair-budget example.
Property taxes
Understand the 2% rule, temporary value reductions, tax-bill charges and the steps to take when your county assessment looks too high.
Family stories
Careful saving, a patient search and a payment that fit helped Yasandra find her first home in Roseville.
Home equity
Explore a home equity loan or HELOC for renovations, debt consolidation or a planned expense, with an option that may let you keep your first mortgage.
Real Scenarios
A real loan-file clarification shows why the existing loan type and payoff matter before estimating available reverse-mortgage proceeds.
Real Scenarios
A real open-house question: where to start, how to check the cash gap, and what to confirm before relying on an advertised assumable loan.
AI in Real Estate
AI can help mortgage companies find suspicious patterns. It can also help criminals create convincing documents, messages and voices. Here is what that means for your loan file and the money you send at closing.
Mortgage Guides
A late credit request can squeeze both closings. See how negotiating on the sale and the purchase helped one homeowner, plus the tradeoffs of putting less down or using lender credits.
First-Time Buyers
Keep your payment budget, loan comparison and closing timeline clear when mortgage pricing changes.
Housing & Communities
A September 2026 look at Placer One: 14 builder neighborhoods, advertised starting prices, the community’s history and the parks, town center and campus still to come.
First-Time Buyers
A practical way to compare FHA, VA and conventional financing, including the money needed beyond your down payment.
Housing & Communities
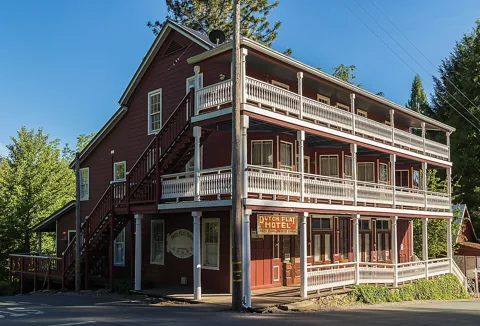
Plan a foothill visit with hotel rooms, dining, a Main Street walk and seasonal museum details.
Photo creditLocal Housing
A quick look at pricing, move-in timing and builder incentives to help you plan your next community visit.
Housing & Communities
August sales improved, builders are using incentives, and financing grew more expensive this week. Here is what that combination means when you tour a new home.
Real Scenarios
A client's unexpected check explains California supplemental property taxes, escrow refunds and the questions to ask before spending the money.
Real Scenarios
A working S corporation example explains depreciation add-backs, ownership, cash flow and why a $16,159 monthly estimate still needs underwriting review.
AI in Real Estate
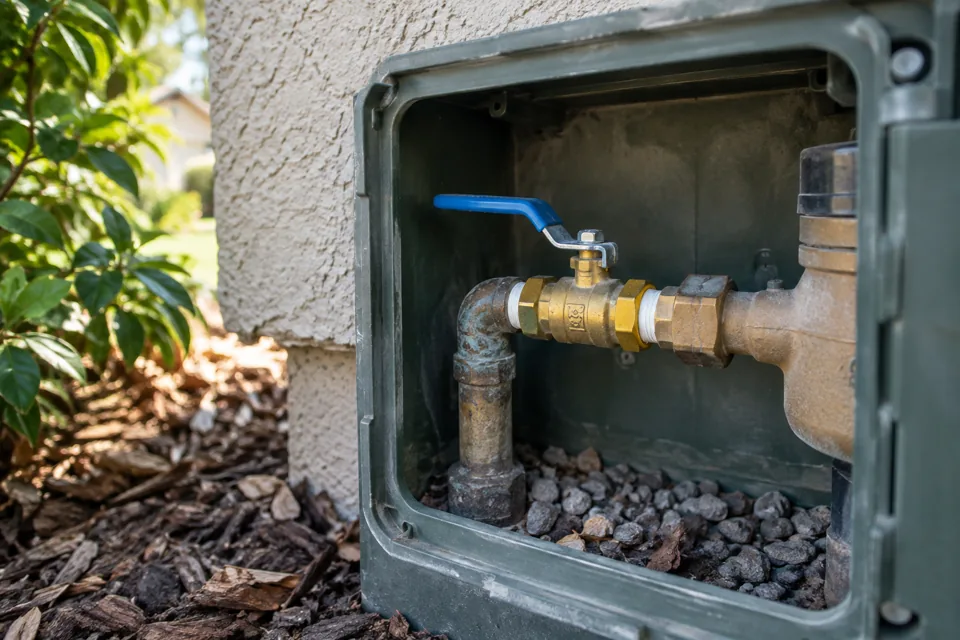
AI leak monitors can learn your household’s water habits. Ask about installation, learning periods and offline protection before choosing an automatic shutoff.
Reverse mortgages
A guide for financial planners to borrowing capacity, costs, cash needs and the family questions to address first.
Real scenarios
Look at the rental's cash flow and the new payment on your home together before using equity to invest.
Family stories
For Steven and Miranda, a three-bedroom home in Lincoln is the beginning of something they have wanted for years.
Real Scenarios
A phone bill, a financed purchase and a credit-building entry can need different treatment. Here is what I ask the lender to check.
Real Scenarios
Make sure the old car loan is removed and the correct replacement payment is included before relying on your homebuying budget.
Real Scenarios
A clear transfer plan can help your family's gift reach closing without last-minute document questions.
Real Scenarios
Work backward from when the purchase needs the money, then connect the sale, transfer and funding steps.
Real Scenarios
Start with the job timeline and the type of pay. A change of employer does not answer the mortgage question by itself.
Real Scenarios
Use verified gross income for qualification and take-home pay to check what feels comfortable.
Real Scenarios
The first payment and the payment used for approval may be different. Compare the balances, rates and repayment assumptions.
Real Scenarios
The property's supported unit count can change the loan options, pricing and use of rental income.
Real Scenarios
Find out what rent the specific lender will accept before building your home-equity plan around a new tenant.
Real Scenarios
Match each debt with the right documents so the loan reflects what is owed and what is secured by the home.
Real Scenarios
Confirm what the appraisal team needs before treating a program change as a simple report correction.
Real Scenarios
An earlier date can mean another signing and more costs. Here is how we weighed that choice in one transaction.
Real Scenarios
Separate real business income from transfers and borrowed money before comparing a bank-statement loan.
Home equity
Connect the home-equity borrowing with the commercial lender's funding requirements and your personal budget.
Real Scenarios
Compare the changed lines, ask why they moved, and follow any correction through to cash to close.
Real Scenarios
Signing authority and borrower identification are separate tasks. Give the family a clear checklist for both.
Real Scenarios
A Roseville buyer with $120,000 income and a 680 credit score compares duplex rent, FHA and conventional down payments, and occupancy requirements.
Real Scenarios
Start with the solar contract. Ownership, financing, leases and power agreements can create different questions for the loan.
Real Scenarios
Ask which cost test is involved, then compare the payment and upfront cost of the available options.
Real Scenarios
Check the documentation rules and the actual business income before choosing between one year and a two-year average.
Real Scenarios
A rental can cover the lender's housing payment and still leave an ownership budget short. Here is the math.
Real Scenarios
Put the appraisal's status beside the contract deadline, with your agent involved before time runs out.
Real Scenarios
Compare the statement lines first. Taxes, insurance, rate changes and credit-line activity can affect the bill differently.
Real Scenarios
Check your credential and employment situation, then compare the specialized program with your other mortgage options.
Real Scenarios
Compare the larger loan, lower rate, mortgage insurance and cash left after closing as complete choices.
Real Scenarios
Turn points and seller credits into dollars to see what the buyer still needs to bring to closing.
Real Scenarios
Compare the payment after temporary help ends with the cost of buying a lower ongoing rate.
Real Scenarios
Work backward from the monthly payment you want, including the costs that come with the actual home.
Real Scenarios
The existing mortgage, new second loan and ownership change need a closing sequence all the right parties can accept.
Real Scenarios
How I work backward from a $140,000 buyout to the cash actually left after loan costs, debts and taxes.
Real Scenarios
Find out whether another person's payment history can help your qualification, without confusing that with release from the old loan.
Real Scenarios
Follow the company's payments and accounting records before deciding how the car loan belongs in your mortgage calculation.
Real Scenarios
Choose the draw plan around the monthly support and reserves you need, not just the biggest credit-line number.
Real Scenarios
Connect the family buyout, ownership transfer and verified retirement income before relying on a refinance.
Real Scenarios
Review signing authority early so the family's housing plan is not held up by unanswered document questions at closing.
Real Scenarios
Compare the cost of the repair, the cost of waiting and the cost of changing loans before taking a shortcut.
Real Scenarios
See how other debts use the payment budget and how paying them off changes the cash left for your goal.
Real Scenarios
Define the total-payment target first, then calculate the paydown and confirm what the servicer will allow.
Real Scenarios
Put the refinance costs beside the monthly improvement, and compare keeping the current loan too.
Market Updates
July PCE inflation remained elevated while income, durable-goods orders, and revised second-quarter growth defined Wednesday's market backdrop.
Market Updates
July new-home sales were estimated at a 607,000 annualized pace as available supply reached 9.6 months, while a 4.70% 10-year Treasury yield and a full economic calendar shape the rate backdrop.
Market Updates
The 10-year Treasury closed Monday at 4.70%, U.S. stocks finished mixed, and representative mortgage averages remained above their August 17 comparison before new-home sales, durable-goods orders, GDP, and Jackson Hole.
Market Updates
The representative Conventional observation was 6.698%, while the August 19 Treasury close put the 10-year yield at 4.65% and the 30-year yield at 5.19%.
Market Updates
The representative Conventional rate averaged 6.750%, while July housing starts fell and bond-market pressure kept the mortgage backdrop cautious.
Market Updates
The latest official 10-year Treasury close was 4.68% on August 14 and the current representative Conventional rate averages 6.743% as oil headlines coincide with higher longer yields.
Market Updates
The 10-year Treasury finished Friday at 4.68%, while the latest representative Conventional rate averages 6.653% before key housing data and Federal Reserve minutes.
Rates & Economy
The most important interest rate for home buyers is not the one most people are watching
Rates & Economy
Retail sales fell, value stores stayed busy, and both signals can be true
AI in Real Estate
Data centers promise investment and jobs, but communities are asking who pays for the power, roads, and housing
Market Updates
July retail sales fell 0.6%, underlying producer prices rose 0.4%, and the latest representative Conventional rate averages 6.653%.
Market Updates
July retail sales fell 0.6% to $763.6 billion, the 10-year Treasury eased near 4.62%, and today's representative Conventional rate is 6.73%.
Market Updates
July producer prices were unchanged, a core measure rose 0.4%, the 10-year Treasury was near 4.67%, and the latest daily Conventional index was 6.74%.
Market Updates
July inflation matched forecasts, the 10-year Treasury held near 4.67%, and the latest daily mortgage indexes were 6.79% Conventional, 6.31% FHA, and 6.32% VA.
Market Updates
Oil climbed again and the 10-year Treasury moved near 4.73% before Wednesday's inflation report, creating a less friendly morning backdrop for mortgage pricing.
Market Updates
July payrolls fell by 23,000 and prior months were revised lower. The 10-year Treasury closed Friday at 4.65%, while this week’s CPI and PPI reports now hold the next major test for mortgage rates.
Market Updates
Payrolls fell by 23,000 in July, prior months were revised lower, and wage growth cooled. Treasury yields dropped as markets reduced near-term tightening expectations, a rate-friendly move paired with a less reassuring employment backdrop.
Market Updates
Initial jobless claims stayed historically low while continuing claims climbed, productivity improved, and labor costs remained contained. The mix helped bonds at the margin, but elevated mortgage rates continued to restrain housing demand.
Market Updates
July services activity stayed firm while employment contracted and price pressure accelerated. Treasury kept auction sizes steady, leaving mortgage markets with modest relief, but no inflation all-clear.
Loan Program Updates
VA published a change clarifying when invoices or supporting documents are required for itemized fees and charges.
Loan Program Updates
VA guidance addressed the effect of certain home energy efficiency ratings on underwriting decisions.
Loan Program Updates
HUD opened a request for information about updating long standing single family minimum property requirements.
Loan Program Updates
HUD Mortgagee Letter 2026-06 updates an operational feature of the Limited 203(k) rehabilitation program.
Loan Program Updates
FHA confirmed its intention to enable additional eligible credit scoring models alongside Classic FICO.
Loan Program Updates
CalHFA has published updates covering Dream For All, refinance, manufactured housing, income limits and a UC shared appreciation program.
VA Loans
A practical starting point for eligibility, entitlement, cash needs, property expectations and team coordination.
Mortgage Guides
A documentation framework for business owners, independent professionals and investors.
Mortgage Guides
How to prepare a property improvement plan before comparing financing choices.
Mortgage Guides
A concise handoff structure that improves speed without placing sensitive information in casual channels.
Mortgage Guides
How to prepare assets, income, reserves, ownership interests and property context for a larger loan review.
Home Equity
A decision framework for revolving access, fixed proceeds, payment stability and preserving the existing first mortgage.
Reverse Mortgages
What homeowners and families should discuss about occupancy, costs, responsibilities, alternatives and counseling.
First-Time Buyers
How to organize down payment, closing costs, reserves, inspections and moving expenses before choosing a target price.
Market Updates
Oil fell sharply on possible progress at the Strait of Hormuz while softer trade and hiring data helped long-term bonds, even as Palantir and Caterpillar showed that AI investment remained powerful.
Local Housing
Water, septic, wells, access, power, solar agreements and outbuildings can shape both due diligence and financing.
Local Housing
A practical question list for buyers and real estate professionals before a property becomes emotionally expensive.
Local Housing
Insurance, utilities, wildfire context, commute patterns, taxes and property condition can vary sharply across nearby communities.
Local Housing
A repeatable method for checking planning documents, active projects, transportation and public meeting records.
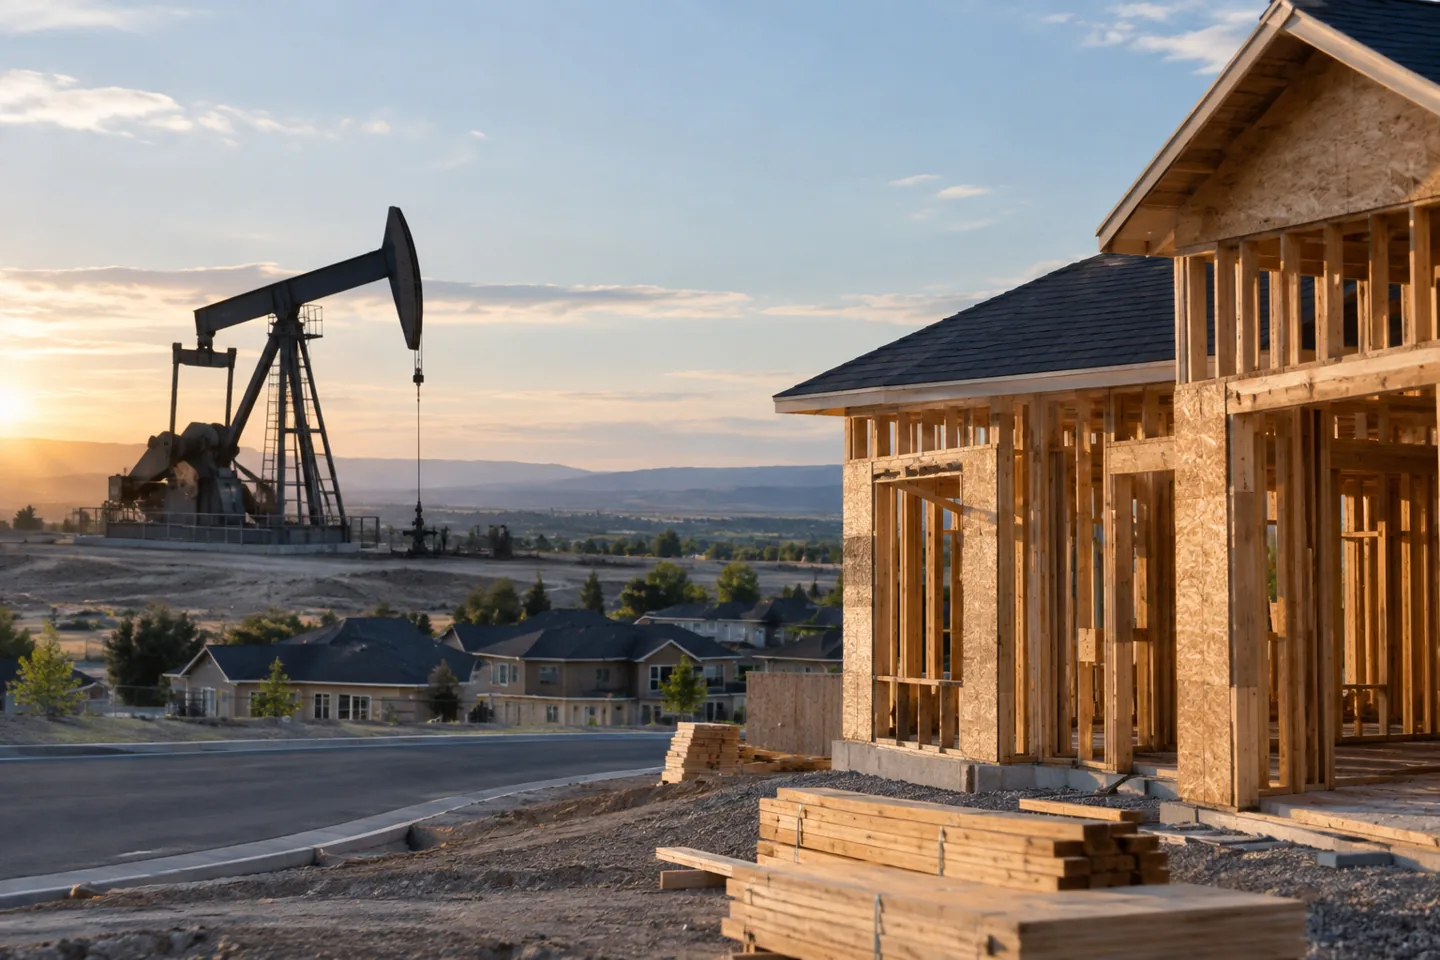
Market Updates
Diplomacy removed part of the oil war premium while the 10-year and 30-year Treasury yields remained high enough to constrain mortgage affordability.
Market Updates
A wild July ended with stronger oil, expensive gasoline, and sharply divided technology earnings, while long yields kept pressure on housing.
Market Updates
Strong artificial-intelligence earnings lifted stocks, but the bond market treated the Fed's divided hold as insufficient protection against inflation.
Market Updates
A 9 to 3 decision, a 7.3% jump in Brent crude, and a rise in the 10-year Treasury to 4.68% denied housing the relief implied by the word hold.
Market Updates
Energy retreated below its recent peak while technology shares and Middle East supply risk kept financial conditions unsettled one day before the Fed announcement.
Market Updates
WTI settled at $82.61, stocks split, and investors assigned meaningful odds to a rate hike ahead of the Federal Reserve decision.
Market Updates
Long-term financing stayed expensive while a major government software agreement showed that selected investment remained powerful before the Fed meeting.
Market Updates
West Texas crude settled near $90.50 while the 10-year yield reached its highest level of the year, combining inflation pressure with weaker mortgage affordability.
Market Updates
A renewed energy shock pushed long yields and mortgage pressure higher while Alphabet's earnings kept the artificial-intelligence investment debate alive.
Market Updates
America's largest homebuilder showed that buyer interest could remain real while elevated mortgage rates, incentives, and affordability constrained transactions.
VA Loans
Learn which surviving spouses may have a VA home loan eligibility path, how the COE process works, and what the lender still needs to review.
VA Loans
Compare the VA IRRRL and VA cash-out refinance. See which existing loan, occupancy, appraisal, equity, cost, and benefit questions matter.
VA Loans
Find official paths for the Native American Direct Loan, VA adapted housing grants, and VA help when mortgage payments become difficult.
VA Loans
Learn how a VA Interest Rate Reduction Refinance Loan works, who may be eligible, what it costs, and how to judge the real benefit.
VA Loans
See how the VA funding fee works, who may be exempt, current fee percentages, what can be financed, and which closing costs may still apply.
VA Loans
Understand full and remaining VA entitlement, using the VA benefit again, restoration, and when county loan limits still matter.
VA Loans
Learn who may qualify for a VA home loan, what a Certificate of Eligibility shows, and how to request a COE without confusing it with loan approval.
VA Loans
Learn how a VA cash-out refinance may access home equity or replace a non-VA mortgage, plus the appraisal, occupancy, cost, and approval questions.
VA Loans
See how buying a home with a VA-backed loan works, from COE and budget planning through the offer, appraisal, underwriting, and closing.
VA Loans
Understand what a VA appraisal does, how it differs from a home inspection, what happens with low value or repairs, and which homes may be eligible.
VA Loans
Understand VA home loan benefits, eligibility, costs, buying, and refinancing. Get straight answers from Nick Cunningham, NMLS #907393.
Home Equity
Follow the second-mortgage process from the first conversation through disclosures, property review, underwriting, closing, and servicing.
Home Equity
Use a balanced decision guide to compare the goal, payment, time, resilience, and alternatives before borrowing against your home.
Home Equity
Compare a HELOC and home equity loan for repairs or renovations, including project timing, staged draws, overruns, payments, and risks.
Home Equity
See how a closed-end home equity loan works, what a fixed payment does and does not solve, and how it compares with a HELOC or refinance.
Home Equity
Learn how HELOC draw and repayment periods work, why rates and payments can change, what fees may apply, and when access can be restricted.
Home Equity
Learn what changes when other debt moves onto the home. Compare the new term, total cost, payment, old-account plan, and alternatives.
Home Equity
Review second-mortgage fees, payment changes, HELOC access risk, tax cautions, rescission, and the foreclosure risk of debt secured by your home.
Home Equity
Compare three ways to borrow against home equity, including what happens to the first mortgage, payment structure, fees, and future flexibility.
Home Equity
Compare HELOCs, home equity loans, and refinancing. Learn what a second mortgage changes, what it costs, and which risks belong in the decision.
Agent Resources
Pre-offer mortgage support for California real estate agents: property fit, price, credits, appraisal, timing, lender calls, and financing assumptions.
Agent Resources
A practical financing review for California listing agents: lender questions, offer terms, program myths, property fit, appraisal, credits, and communication.
Agent Resources
A real estate agent's guide to HECM for Purchase: buyer contribution, property fit, offer planning, ongoing obligations, family questions, and early scenario review.
Agent Resources
A clear mortgage communication plan for California real estate agents from accepted offer through appraisal, conditions, closing figures, and funding.
Agent Resources
A practical buyer-financing handoff for California real estate agents: goals, payment comfort, cash-to-close, review stages, documents, and property questions.
Agent Resources
Practical mortgage support for California real estate agents: buyer preparation, offer conversations, transaction updates, listing-side questions, and local resources.
Market Updates
The Bank of America chief executive's higher-for-longer view collided with oil relief and a crowded policy calendar, leaving mortgage markets defensive.
First-Time Buyers
Clear answers to first-time homebuyer questions about credit, down payments, preapproval, assistance, monthly payments, offers, and closing.
First-Time Buyers
Learn how income, debts, credit, taxes, insurance, HOA dues, and your own comfort zone shape an affordable first-home payment in California.
First-Time Buyers
See the first-time homebuying process from budget and preapproval through offers, underwriting, final review, signing, and closing.
First-Time Buyers
Compare conventional, FHA, VA, USDA, and assistance-linked home loan paths in plain English. See the trade-offs that matter before you choose.
First-Time Buyers
Learn how California down payment assistance can work, what eligibility and repayment rules to check, and how Nick helps compare the full loan structure.
First-Time Buyers
Learn what first-time homebuyers may need for a down payment, closing costs, prepaid expenses, and reserves, plus ways funds may be sourced.
First-Time Buyers
Buying your first home in California? Nick Cunningham explains affordability, down payments, loan options, assistance, and every step in plain English.
Agent Resources
A sourced guide to recurring questions about VA-backed purchase offers.
Agent Resources
Official Sacramento-area starting points for homebuyers, homeowners, agents, and referral partners.
Agent Resources
A printable worksheet for planning the sale of a current home and the next purchase as one decision.
Agent Resources
A practical first-time buyer conversation guide for real estate agents and prospective homebuyers.
Market Updates
WTI finished its strongest week in months near $82 while short Treasury yields stayed restrictive, forcing housing to weigh healthy demand against a renewed energy shock.
Market Updates
Regional manufacturing surged far beyond expectations while oil below $80 offered a competing inflation signal, leaving housing with a mixed market day.
Market Updates
Treasury yields eased after softer inflation evidence, giving mortgage markets a friendlier direction without proving that the longer trend had changed.
Market Updates
The Federal Reserve chair put elevated mortgage costs and weak housing beside a firm inflation commitment, while supply proposals highlighted how slowly new homes reach buyers.
Market Updates
Energy inflation returned, South Korea's KOSPI fell 8.95%, and modest U.S. retail growth left mortgage markets balancing price pressure against global risk.
Market Updates
A record foreign listing, resilient travel demand, contained oil, and a 10-year Treasury near 4.57% made July 10 a study in strong investment and stubborn financing costs.
Reverse Mortgages
Short, dated, sourced notes on reverse mortgage (HECM) policy, programs, and local items as they land.
Reverse Mortgages
Compare the reasons a HECM may help, the situations where it may not fit, and the alternatives worth putting side by side.
Reverse Mortgages
See how a HECM uses home equity, how the balance grows, how proceeds may be received, what homeowners still pay, and when the loan is repaid.
Reverse Mortgages
See how eligible buyers age 62 or older can combine personal funds with a HECM to buy a principal residence and keep more cash available.
Reverse Mortgages
How home equity can support a retirement plan, what a HECM costs, and the questions to explore with your clients.
Reverse Mortgages
Help a parent evaluate a HECM without taking over the decision. Learn the questions to ask about the home, costs, spouse protections, servicing, and the estate.
Reverse Mortgages
Mortgage-side support for CPAs reviewing HECM loan proceeds, interest, property charges, liquidity, documentation, and client coordination.
Reverse Mortgages
Prepare for HUD-approved reverse mortgage counseling and follow the HECM process through appraisal, underwriting, closing, and servicing.
Reverse Mortgages
Understand HECM closing costs, the growing loan balance, property charges, occupancy rules, non-recourse protection, and the questions families should ask.
Reverse Mortgages
Learn how an FHA-insured HECM reverse mortgage works, what it costs, what homeowners must keep paying, and when another option may fit better.

Checklists & Worksheets
Organize the questions that matter before a VA-backed offer is written.
Checklists & Worksheets
Create a calm, informed family discussion before deciding whether a HECM deserves a closer look.
Checklists & Worksheets
Compare a HELOC, home equity loan and refinance without focusing on payment alone.
Checklists & Worksheets
Plan beyond the down payment before you start shopping.
Checklists & Worksheets
Use better financing questions before a buyer reaches the offer stage.
Homeowner Guidance
Know your filter, notice changes early, and make the next service visit more useful.
Homeowner Guidance
Compare comfort, installation work and operating assumptions before replacing heating and cooling equipment.
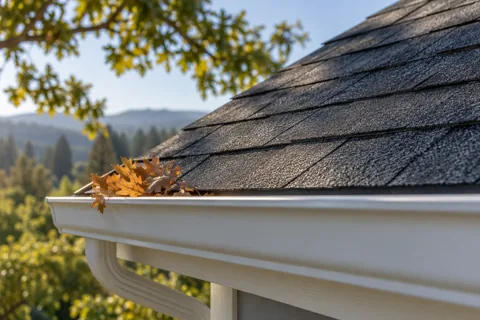
Homeowner Guidance
Spot changes, document concerns and ask a roofer better questions while keeping your feet on the ground.
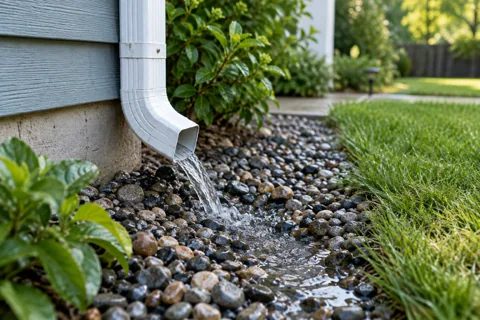
Homeowner Guidance
A clean gutter is only part of the picture. Look at downspouts, drainage and safe access too.
Homeowner Guidance
Understand ownership, payment changes, roof work and resale responsibilities before committing.
Homeowner Guidance
Use production records and manufacturer guidance to decide what maintenance is worth investigating.
Homeowner Guidance
Plan around essential loads, outage expectations and installation details before comparing battery packages.
Homeowner Guidance
Use a short observation routine to spot possible leaks and prepare a useful service request.
Homeowner Guidance
Make a household water plan with clear labels, safe access and the right emergency contacts.
Homeowner Guidance
Gather the right records, notice changes and plan professional maintenance for your specific equipment.
Homeowner Guidance
Build a practical plan for the structure, surrounding property and the people who live there.
Homeowner Guidance
Check coverage, testing instructions and emergency responses before an alarm becomes confusing.
Homeowner Guidance
Make exits, meeting places and household responsibilities clear before an emergency.
Homeowner Guidance
Choose a comfortable room, plan filtration and keep evacuation and heat safety in view.
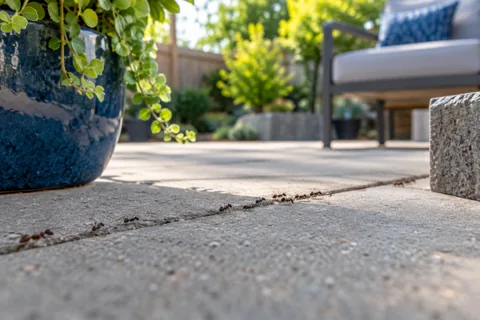
Homeowner Guidance
A practical way to describe a pest problem, reduce attractants and evaluate service recommendations.
Homeowner Guidance
Separate identification, treatment and wood repair so you understand the proposed work.
Homeowner Guidance
Review access, supervision and emergency preparation alongside ordinary pool maintenance.
Homeowner Guidance
Know what gets tested, what is included and which responsibilities remain between visits.
Homeowner Guidance
Match plants, tasks and service expectations to the way you use your outdoor space.
Homeowner Guidance
Find misdirected spray, damaged heads and schedule problems without guessing at watering needs.
Homeowner Guidance
Use a documented assessment to understand pruning, health concerns and removal recommendations.
Homeowner Guidance
Review cooling, irrigation and the changes winter left behind, then prioritize the work.
Homeowner Guidance
Plan comfort, outdoor work and an alternative place to cool down before a heat event.
Homeowner Guidance
Use the transition toward wetter weather to organize drainage, heating and outstanding maintenance.
Homeowner Guidance
Prepare for your address and elevation rather than assuming every Placer County home faces the same conditions.
Homeowner Guidance
Start room by room and create a usable record of belongings before a loss.
Homeowner Guidance
Use the renewal to review the home, limits, exclusions and changes in your household.
Homeowner Guidance
A clear scope, license checks and a payment plan make estimates easier to evaluate.
Homeowner Guidance
Get oriented, organize records and separate urgent needs from projects that can wait.
Homeowner Guidance
Keep the homeowner role to observation, safe use and arranging qualified electrical help.
No articles match yet. Try another word or choose all topics.
Connections before mortgages
Tell us what’s on your mind. Buying, refinancing, or exploring your options starts with a conversation.
Prefer another way? Call us · Email us · Send a note
Homeowners insurance helps protect your home and belongings against covered losses. In California, start checking insurance availability and cost early in a home purchase, and review coverage before renewal. A mortgage preapproval is not confirmation that a particular property can be insured. Compare coverage, exclusions, deductibles and the total cost, then have your lender review the proposed policy.
Explore California insurance guidance